The dealmaker who prices companies and moves capital — a trade running from Medici Florence to today's pitch decks, paid for trust when billions change hands.
Also called: Dealmaker · M&A banker · Corporate financier
Investment Banker: The dealmaker who prices companies and moves capital — a trade running from Medici Florence to today's pitch decks, paid for trust when billions change hands.
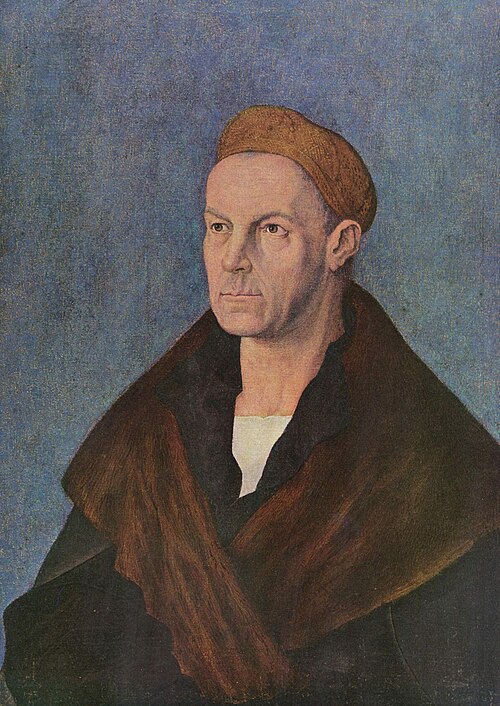
Investment banking is the trade of standing between capital and the people who need it: advising companies, governments and funds when they buy, sell, merge or raise money, and underwriting the stocks and bonds that pay for it. The job is older than its name — Renaissance Florence's merchant banks financed kings and popes through bills of exchange, and the Medici, Fugger and Rothschild houses ran recognizably modern versions of the business centuries before Wall Street existed.
The modern firm is a pyramid apprenticeship. Analysts fresh from university build the models and the hundred-page pitch books; associates and vice presidents run the deal process; managing directors win the clients and take the 2 a.m. phone call when a transaction wobbles. Pay is extreme at every level and so are the hours: a leaked 2021 survey of Goldman Sachs first-year analysts reported working weeks averaging around 95 hours.
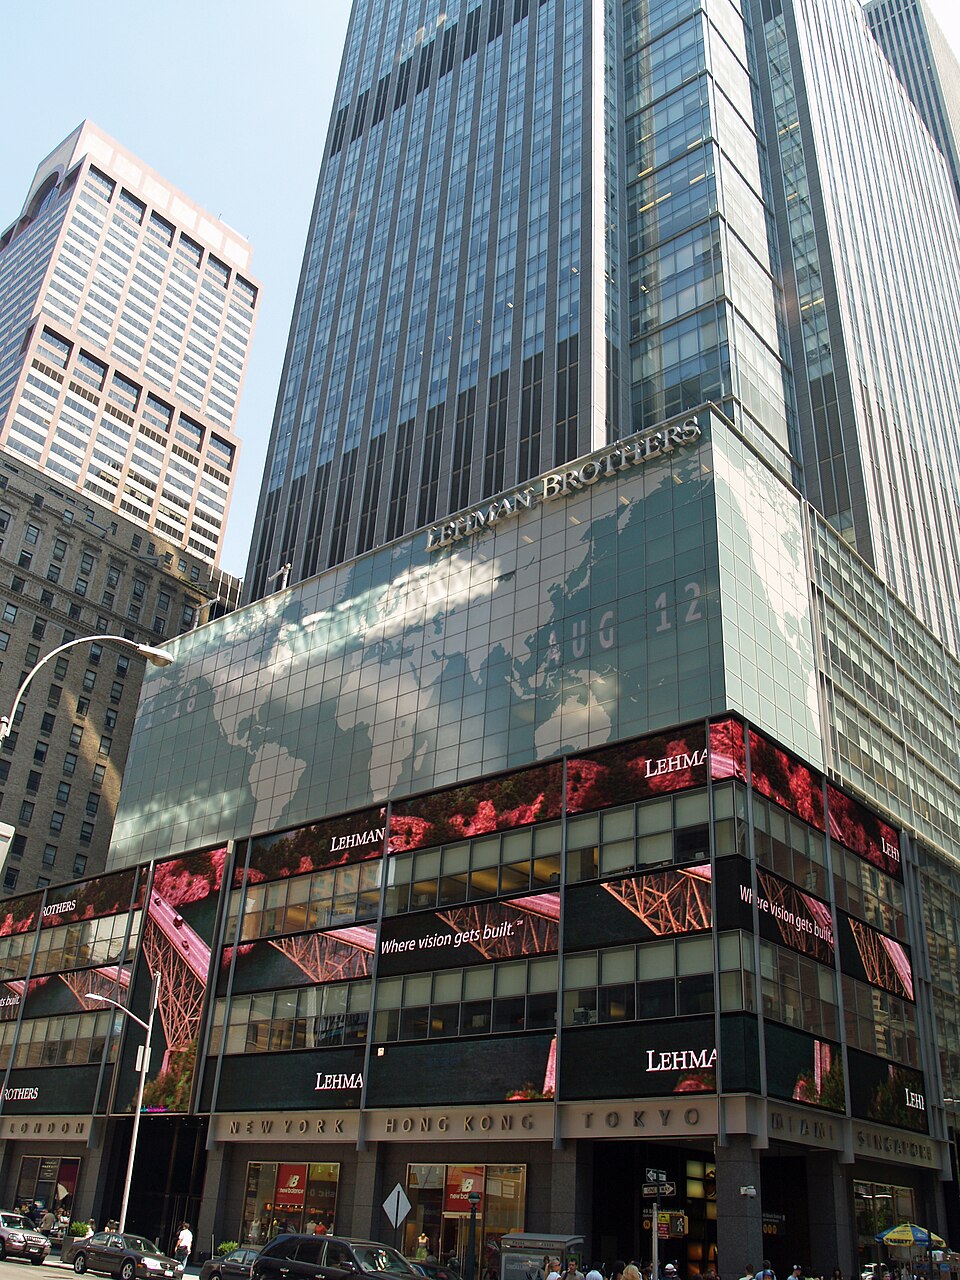
This page follows the trade from the ruin of Florence's Bardi and Peruzzi banks in the 1340s through Jakob Fugger's purchased empire, J. P. Morgan's locked library, the invention of the Eurobond, London's Big Bang and the fall of Lehman Brothers. It covers how people actually get hired today, what the junior years demand, who reached the top of the profession — from Osaka to Lagos to Wall Street — and how much of the work AI can realistically absorb.
Inside the profession
Investment banking is the intermediary craft of advising on capital — mergers, issuances, restructurings — under deadlines set by markets, regulators and clients who will remember who mispriced the risk.
Advice under incomplete books
Bankers build models, comps and pitch materials from imperfect information: management guidance, public filings, industry chatter and diligence rooms that never contain every liability. The craft is not prediction theater; it is framing valuation ranges, deal structures and process risks so a board can decide with eyes open. A wrong multiple or a missed covenant can destroy a client's leverage in negotiation. Juniors live in spreadsheets and slide decks; seniors live in judgment about when a number is robust enough to put in front of a committee. Credibility compounds across deals and collapses on one careless deck.
Process is the product
Sell-side auctions, IPOs, debt issuances and restructurings are choreographed: teasers, NDAs, management presentations, Q&A, markups and signing. Timing, information control and buyer sequencing often matter as much as the headline valuation. A banker who mishandles a leak, a conflicting mandate or a regulatory filing can kill a deal that the model said should clear. Relationship banks compete on coverage access; boutiques compete on focus. Across both, the invisible skill is keeping dozens of counterparties moving without letting process noise become price noise.
Regulation and reputation
Capital markets sit inside securities law, conflict rules, Chinese walls and disclosure duties that vary by jurisdiction. A banker advising a bidder while another desk holds a conflicting position, or stretching a 'fairness' narrative past the evidence, invites enforcement and permanent client distrust. Post-2008 reforms, MiFID II research economics and ESG disclosure regimes changed how research, sales and advisory interact. The profession's public image is deal swagger; its private constraint is that a license to advise on public capital is conditional on process integrity that can be audited after the fact.
Technology compresses the junior hours, not the stakes
Data rooms, automated comps, AI draft memos and faster market screens reduce some formatting labor that once filled all-nighters. They do not remove the need to notice when a model assumes a margin the industry has never sustained, or when a buyer list is politically incomplete. Clients still hire banks for access, judgment under ambiguity and the willingness to put a name on a recommendation. The enduring scarcity is senior coverage who can tell a CEO that the timing is wrong — and juniors who will escalate a broken assumption before it reaches the board.
How the work branches
Five common shapes of the same title — specialty, setting or career path.
Bulge brackets and boutique firms
M&A advisory
Runs sale processes, buy-side mandates and merger structuring from teaser through signing and announcement.
IPO and follow-on desks
Equity capital markets
Prices and syndicates equity issuances, coordinating issuers, investors and research under market windows.
Issuance and sponsor coverage
Debt capital markets / leveraged finance
Structures bonds and loans, balances covenants and investor demand, and navigates refinancing cycles.
Distressed and turnaround situations
Restructuring banker
Advises creditors or companies when capital structures break, often under court or covenant pressure.
Sector teams inside banks
Industry coverage officer
Owns long-term client relationships in a vertical and originates mandates across product specialists.
How it reads by country
Same craft, different gatekeeping, status and daily texture — rewritten for readers in each language.
United States — Wall Street and elite pipeline
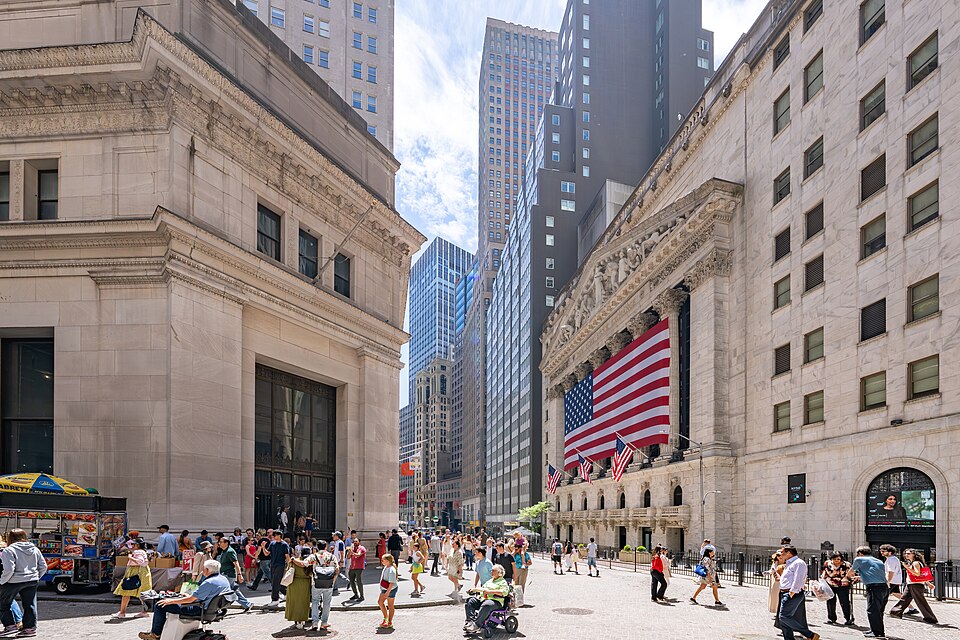
US investment banking remains centered on New York with strong West Coast tech coverage. Analyst programs, bulge-bracket hierarchies and sponsor-backed M&A dominate early careers; FINRA licensing and SEC process shape the compliance texture of deals.
South Korea — chaebol deals and Seoul houses
Korean bankers work across domestic securities houses and global banks on chaebol restructurings, IPOs and cross-border acquisitions. Hierarchy, long hours and relationship coverage of major groups define advancement; bilingual deal execution is a frequent requirement.
Japan — megabanks and cross-border advisory
Japanese investment banking mixes megabank coverage cultures with global firms in Tokyo. Domestic M&A, equity issuance and outbound acquisitions require patience with consensus decision-making and careful navigation of corporate group relationships.
Germany — Frankfurt and Mittelstand M&A
Frankfurt anchors capital-markets work, while Mittelstand sell-side mandates feed a deep mid-market advisory culture. Bankers balance EU prospectus and takeover rules with family-owned governance norms that differ from US sponsor processes.
United Kingdom — City of London as European hub
London remains a major ECM/DCM and cross-border M&A center despite regulatory change after Brexit. Analyst intakes, FCA conduct rules and a dense sponsor/private-equity ecosystem structure careers across bulge brackets and boutiques.
Singapore — Southeast Asian deal bridge
Singapore hosts regional coverage for ASEAN issuers, funds and cross-border M&A. Bankers often work multilingual deals under MAS oversight, connecting local corporates to global capital with time-zone advantages across Asia.
From the archive
Commons CC/PD images self-hosted for this profession.
Why attitude matters here
Investment banking skills produce a model and a process; whether the client hears the real risk range — or a story optimized to win the mandate — depends on attitudes that only show under fee pressure and all-night revisions.
The client cannot rebuild the model from the pitch alone
Boards hire banks because they lack the time and market access to stress every assumption themselves. If a banker hides a fragile margin, cherry-picks comps or presents a point valuation as if it were a certainty, the client may discover the truth only after announcement, when reputation and fiduciary exposure are already live. Competence without candor is structurally hard for the buyer of advice to detect in the room.
Conflicts are profitable until they are public
Sell-side fees, stapled financing, dual mandates and research interactions create situations where the bank's interest and the client's can diverge quietly. Whether a banker surfaces the conflict early, walls it properly and declines the awkward mandate — or hopes the process finishes before anyone asks — is an attitude test with regulatory and career consequences. The rules exist on paper; living them when the fee is large is the actual craft.
Junior errors scale through senior silence
A wrong share count, a stale trading multiple or a mis-tied footnote can reach a CEO if no one in the chain treats verification as non-negotiable at 3 a.m. Seniors who punish delay more than error teach juniors to ship fragile decks. The profession's outcomes are therefore as much about whether someone will slow a process to fix a number as about who can build a DCF the fastest.
Stances that hold up under pressure
Five concrete postures the work rewards, not slogans.
Shows the valuation range, not only the number the client wants
Presents the full defensible range and the assumptions that move it — comps, synergies, financing — even when a tighter, more flattering point estimate would make the bake-off pitch easier to win and keep coverage comfortable in the room.
Flags a conflict before the engagement letter is signed
Raises dual-mandate, financing, information-wall or prior-advice issues early enough that the client can consent with eyes open or walk away, rather than discovering the tension mid-auction when unwinding it would embarrass everyone and endanger the fee.
Owns a broken cell before it reaches the committee
Stops a deck when a link, unit, share count or date is wrong, absorbing the political cost of delay and a VP's irritation rather than hoping no one notices in the committee room where a CEO will treat the slide as fact.
Protects process integrity when a leak would help 'their' buyer
Refuses to selectively tip information that would advantage one bidder, even when that bidder is more likely to close, protect the bank's fee and keep the coverage officer's relationship scorecard looking strong for the year.
Tells a CEO the window is wrong
Advises delaying an issuance or sale when market conditions, diligence gaps or regulatory timing make a deal reckless, rather than manufacturing urgency and a false scarcity story to keep the mandate alive through a bad week.
Moments that reveal it
Situations that separate résumé language from how someone actually practices.
A pitch deadline is in four hours and a junior finds that a key comparable's reported EBITDA was restated last week, lowering the implied multiple.
Does the team rebuild the comps and widen the range before the meeting, or leave the flattering figure because the client already likes the number, the competitor pitch is tonight and nobody wants to be the person who slowed the room?
A potential buyer asks informally for color that would violate the information protocol agreed with the seller.
Does the banker refuse, document the request and keep the process clean, or provide soft guidance because that buyer is the most likely to pay and a quick close would lock the fee before another bank reopens the auction?
Winning a bake-off would require implying a valuation the coverage officer privately believes the market will not clear.
Does the banker keep the pitch honest and risk losing the mandate to a competitor's fantasy multiple, or match the fantasy and plan to 'manage expectations' after hiring when the board is already emotionally committed?
An all-nighter produces a board deck with a footnote the associate knows is unsupported, but the VP has already sent it upstairs.
Does the associate escalate immediately and force a correction before the meeting, or stay quiet because challenging the VP after midnight is treated as disloyalty on a team that rewards speed over verification?
Where "calling" turns harmful
"Face time" and calling language as cover for manufactured presence
Banks frame hundred-hour weeks as the price of apprenticeship and owning the deal, then punish juniors who leave when the work is done because empty face time signals loyalty. Passion-for-the-markets talk normalizes sleep deprivation and canceled life, while the model still profits from labor intensity billed to clients as dedication.
The profile
Resists AI42
Pay97
Barrier to entry70
Autonomy35
Demand55
Impact60
How exposed is it to AI?
High
A majority of current junior-banker hours go to tasks AI already performs credibly: assembling presentations, drafting first-cut models and comps, summarizing data-room documents, producing market-update materials. What resists automation is the senior franchise — winning mandates on trust, negotiating against humans, and signing regulated opinions someone must be liable for. The job survives; the pyramid beneath it narrows.
Two things: advise and underwrite. Advisory bankers guide companies, governments and funds through mergers, acquisitions, sales and restructurings; capital-markets bankers raise money for them by underwriting new stocks and bonds and placing them with investors. Investment bankers do not manage individuals' savings or take deposits — the day-to-day work is valuation, negotiation, documents and long client meetings.
Is an investment banker the same as a regular banker?
No. A commercial banker takes deposits and makes loans; an investment banker advises on deals and underwrites securities. The two were legally separated in the United States by the Glass–Steagall Act of 1933 — which split Morgan Stanley out of J.P. Morgan — and although that wall came down in 1999, the jobs, skills and pay structures remain entirely different.
How much do investment bankers earn?
In the United States in 2024, first-year analysts typically earned around $170,000–200,000 in salary plus bonus, and managing directors from roughly $1 million to many multiples of that in strong deal years. London, Frankfurt, Hong Kong and Tokyo pay less at every level, and bonuses — the majority of senior pay — swing sharply with the deal cycle.
What degree do you need to become an investment banker?
A bachelor's degree, almost always from a university the banks actively recruit at; finance and economics are common but not required — London desks hire historians and classicists. There is no pre-hire license: US bankers sit the FINRA Series 79 exam after joining. The MBA is a separate, later door, used mainly by career-changers entering at associate level.
How many hours do investment bankers really work?
Junior bankers commonly work 70–95 hours a week during live deals, including weekends; a leaked 2021 internal survey of Goldman Sachs first-year analysts reported averages around 95 hours and five hours of sleep a night. Hours moderate with seniority, and since 2024 several banks, including JPMorgan, have formally capped junior weeks at roughly 80 hours.
What is a pitch book?
The presentation a bank prepares to win a mandate: valuation analysis, market context, potential buyers or targets, and the bank's credentials, often running to a hundred slides. Analysts and associates assemble them, frequently overnight. A famous irony of the trade is that most pitch books lose — banks routinely pitch many times for every mandate they actually win.
Will AI replace investment bankers?
It is already replacing parts of the junior workload — drafting presentations, building first-cut models, summarizing diligence documents. What it cannot yet do is win a board's trust, negotiate against another human, or take legal responsibility for a fairness opinion. The likeliest outcome is smaller analyst classes and unchanged demand for the senior bankers clients actually hire.
Why do so many analysts leave after two years?
Because the system is built that way. The two-to-three-year analyst program functions as a finishing school for finance: private-equity firms and hedge funds recruit analysts as early as their first year, and corporate development teams take many of the rest. Banks accept the churn — a minority stay to associate, and a small fraction of those eventually make managing director.
Embed this ranking
Paste this code into your blog or site — the ranking stays up to date.