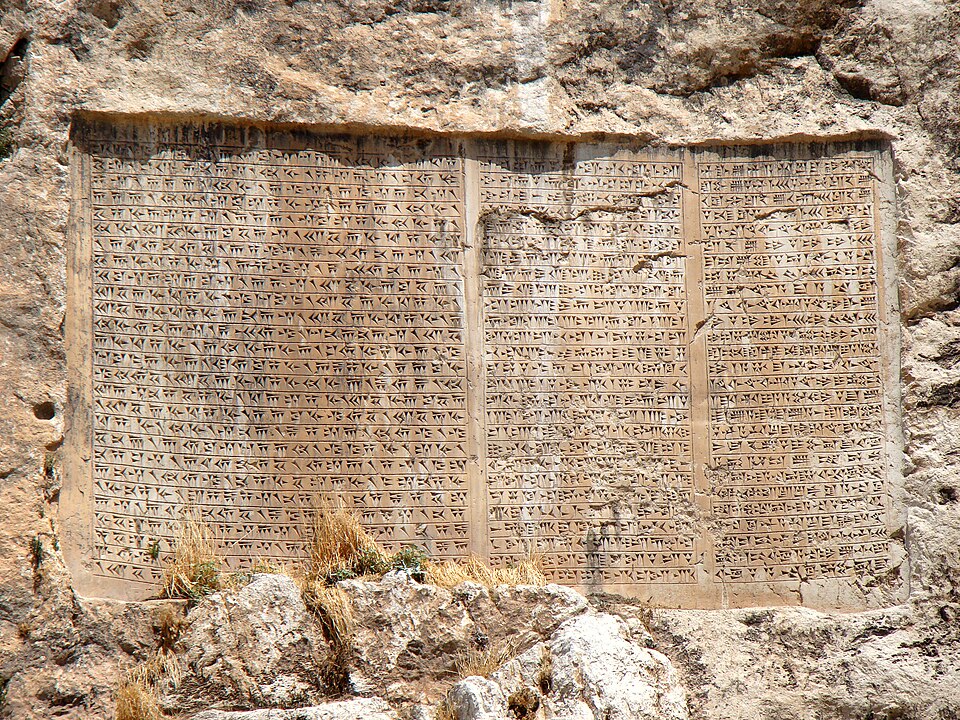
Accounting is older than literature — in fact it produced writing. The earliest tablets from Uruk, in modern Iraq, are not poems or prayers but receipts: barley delivered, sheep owed, rations paid. For five thousand years since, every state, temple, guild and company has needed someone to keep the record of who owes what to whom, and the keeper of that record went by many names — scribe, steward, clerk — before settling on accountant.
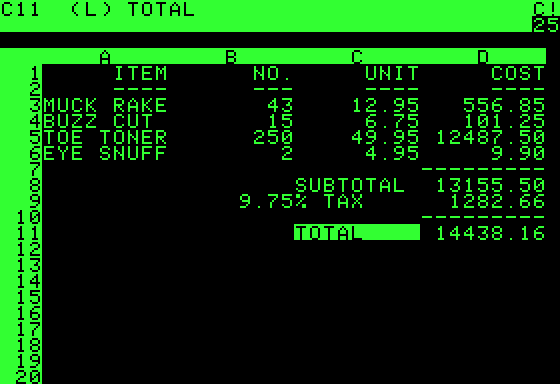
The modern profession is younger and more precisely dated: it begins in 1854, when Scotland's accountants received a royal charter and invented the "chartered accountant," and in 1896, when New York created the first "certified public accountant." Between those dates and now, securities law made the audit compulsory, the spreadsheet swallowed the paper ledger, and a trade of quill-wielding counting-house clerks became a global profession of more than three million credentialed members.
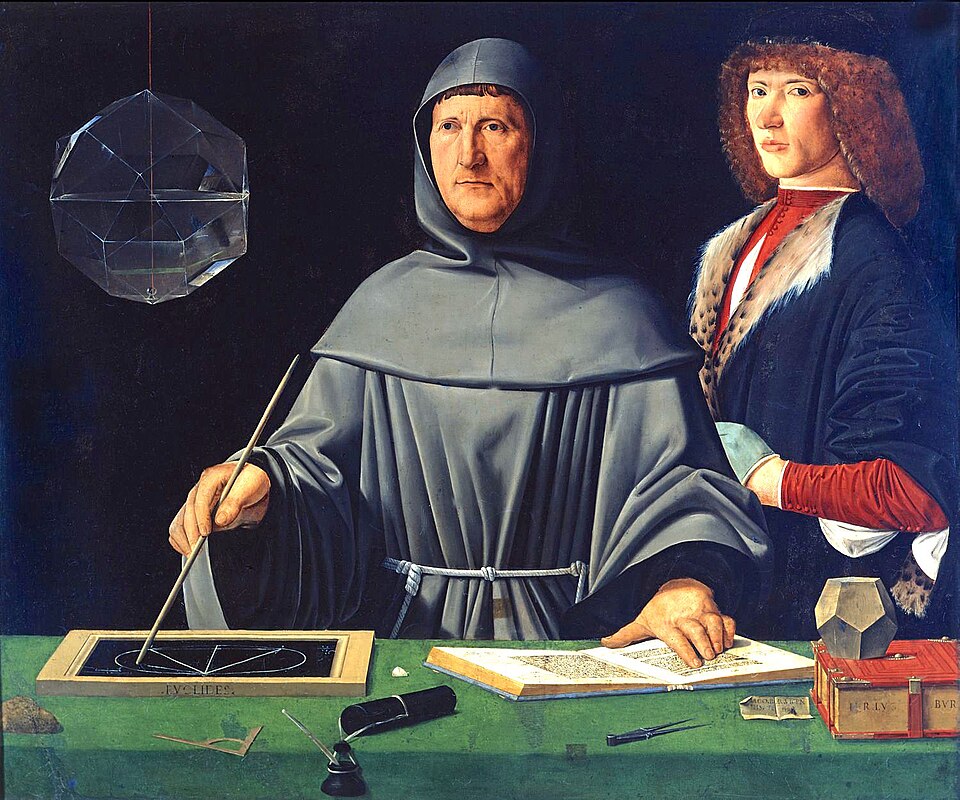
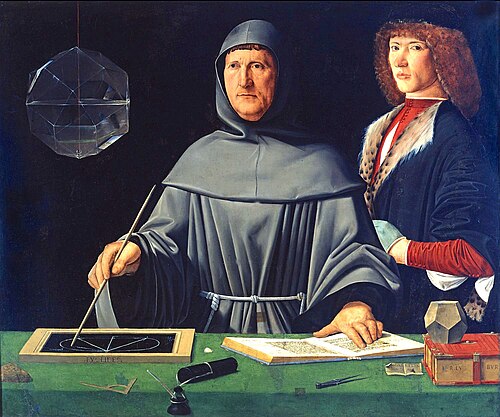
This page follows the craft from clay tokens to cloud software: how double entry spread from medieval Italy to the whole world, what accountants actually do all day and in busy season, who reached the top of the profession — a friar, a potter, a whistleblower — how much the work pays on four continents, and how much of it artificial intelligence can honestly be expected to take.
Inside the profession
Accounting is the craft of making an organization's financial story accurate enough for owners, regulators, managers and future decisions to rely on it.
What the day actually is
Accountants reconcile records, close periods, explain variances, prepare reports, interpret rules and chase information from people who did not realize their decision created a financial consequence. Month-end can mean late nights with bank matches, accruals, intercompany balances and managers asking why a number moved. Much of the work is detective work with deadlines: finding the missing invoice, the misclassified cost, or the control that failed before the statement goes out.
Numbers are not neutral
A ledger is structured judgment applied consistently: when revenue counts, what a cost belongs to, how an asset loses value and what a risk requires disclosure. Accountants protect comparability across periods and make uncertainty visible rather than making a business look better for a quarter. The craft includes knowing which estimate is reasonable, which policy change needs explanation, and when a tidy spreadsheet is hiding a weak assumption that auditors or lenders will later test.
Routes and specialties
Degrees and professional qualifications open many doors, but practical experience builds the trust that lets people rely on a close. Tax, audit, management accounting, forensic work and public finance use related fundamentals with different clients, seasons, rules and ethical risks. A public-practice busy season is not the same job as a corporate controllership or a forensic investigation, even when the software and standards look similar on a resume.
What automation changes
Software already handles routine posting, matching and first-pass report generation, and AI accelerates reconciliation suggestions and draft narratives. Automation raises the premium on controls design, exception handling, interpretation and the ability to explain a number to people who will act on it. Professional skepticism remains the safeguard when data looks tidy: someone still has to ask whether the system measured the right thing under the right rule.
How the work branches
Five common shapes of the same title — specialty, setting or career path.
Corporate finance teams
Financial accountant
Produces statutory statements, closes periods and maintains records under recognized accounting standards.
Operating businesses
Management accountant
Builds budgets, forecasts and cost insight for managers deciding how to run the organization.
Accounting firms and internal audit
Auditor
Tests evidence, controls and financial assertions while preserving independence from the people being examined.
Firms, companies and advisory
Tax accountant
Applies tax law to filings, transactions and planning across constantly changing jurisdictions.
Investigations and finance transformation
Forensic or systems accountant
Follows complex records for disputes or designs the financial systems and controls that make reporting reliable.
How it reads by country
Same craft, different gatekeeping, status and daily texture — rewritten for readers in each language.
United States — CPA licensing and public accounting
CPA requirements vary by state and remain a major credential for audit and public practice. Large firms provide structured training but busy seasons can be intense; industry finance offers a different rhythm.
South Korea — CPA examinations and conglomerates
The CPA path is competitive, with opportunities in accounting firms, financial services and major corporate groups. International standards and global reporting create demand for bilingual technical skill.
Japan — national qualification and corporate finance
Certified public accountants follow a demanding national route, while company accounting careers can grow through long organizational experience. Local practice and international reporting both matter in global firms.
Germany — tax expertise and formal credentials
Tax advisory and statutory audit are strongly regulated professions with demanding examinations. Mittelstand companies create deep in-house roles alongside international firms.
United Kingdom — chartered routes and financial services
ACCA, ICAEW and CIMA pathways structure careers across audit, tax and management accounting. London expands finance opportunities, while regional firms remain important training grounds.
Singapore — regional standards and finance hub
Singapore's finance hub attracts audit, tax and regional-controllership roles. Professionals work across local rules and multinational reporting requirements, often coordinating Southeast Asian entities.
From the archive
Commons CC/PD images self-hosted for this profession.
Why attitude matters here
An accountant's numbers can tie out perfectly and still be a lie, because the job's real test is whether they'll flag the entry that doesn't look right when no one else would notice it either.
Flagging the number that makes the client or boss look bad
An expense that's really personal, a revenue figure recognized too early, or a reserve that's quietly too thin all tie out fine on paper and only become a problem if someone says so out loud. An accountant who raises the issue anyway, even when it's unwelcome to a client or a superior who signs their paycheck, is the reason the numbers mean something; one who lets it pass turns accounting into a formality.
Resisting pressure during the crunch when scrutiny is lowest
Close periods and tax deadlines create exactly the conditions — fatigue, time pressure, a backlog of entries nobody has time to double-check — where a corner is easiest to cut and least likely to be caught. Whether an accountant holds the same standard at hour eleven of a sixteen-hour day that they held at hour one is where the profession's credibility actually gets decided.
Independence from the client who is also the one paying the fee
An auditor or accountant is paid by the very company whose numbers they're supposed to scrutinize, which creates a permanent, structural incentive to go easy. The choice to qualify an opinion or push back on a management estimate despite that financial relationship is the entire point of the role; without it, the credential is just a signature for hire.
Stances that hold up under pressure
Five concrete postures the work rewards, not slogans.
Documents a judgment call at the time it's made, not after
Writes down the reasoning behind an estimate or classification in the moment, rather than reconstructing a justification later if the number is ever questioned by a reviewer, a partner, or an auditor.
Raises a discrepancy before it's asked about
Flags a number that doesn't reconcile the moment it's found and looks into exactly why, instead of hoping it resolves itself quietly in a later entry or waiting to see if anyone else notices it first.
Says no to backdating or reclassifying to hit a target
Refuses to shift an entry into a different period or category solely to make a quarter or a budget line look better than it actually performed, regardless of who is asking for that favor to be done quietly.
Holds the same standard in week one and in week of the deadline
Applies the same level of scrutiny to an entry reviewed at 11 p.m. during a crunch as to one reviewed calmly in a slow month, rather than letting fatigue quietly lower the bar for what passes review that night.
Pushes back on a client's aggressive tax position with a paper trail
States clearly, in writing, when a deduction or position is a stretch rather than a safe read of the rule, instead of going along with it quietly because the client is insistent and the fee is significant.
Moments that reveal it
Situations that separate résumé language from how someone actually practices.
A senior partner wants a number rounded in the client's favor
A number that's technically defensible either way gets nudged toward whatever makes a client relationship easier, at a superior's suggestion. Whether the accountant raises a concern or quietly complies is a direct test of independence.
A discrepancy surfaces two days before the filing deadline
Finding a real problem this late means either a difficult, time-pressured conversation and a possible delay, or letting it slide because everyone just wants the deadline to pass. What the accountant does under that specific time pressure is the tell.
A close friend's small business asks for a favor with the books
A friend or family member running a business wants a personal expense run through it 'just this once.' Treating this the same as any other client relationship, rather than as an exception because the client is a friend, is the test.
Busy season has already stretched to a sixteenth straight day
Exhaustion late in tax or audit season makes a shortcut tempting simply to get through the pile faster. Whether the review at hour sixteen gets the same attention as the review at hour one reveals what the accountant is actually protecting.
Where "calling" turns harmful
Busy-season burnout normalized as professional dues
Public accounting culture frequently treats eighty-hour weeks during tax and audit season as an unavoidable rite of passage rather than a staffing problem, framing the grind as "paying dues" toward partnership instead of compensating the hours worked. "We're all in this together" gets repeated by partners who are not working the same hours as the associates asked to sacrifice weekends for it.
The profile
Resists AI35
Pay62
Barrier to entry52
Autonomy55
Demand78
Impact60
How exposed is it to AI?
High
Task by task, most of traditional accounting work — recording, matching, standard returns, first-draft statements — is automatable with current technology, and much of it is already automated. What resists is the licensed core: audit opinions, contested tax positions, estimates and going-concern judgments, and fraud detection against adversaries who adapt. The realistic future is a smaller, more senior profession reviewing machine output — a real transformation, well short of replacement, and cushioned for now by a worldwide shortage of qualified entrants.
Accountants record, summarize and verify financial information. The work splits into strands: financial accounting produces the statements outsiders rely on; management accounting produces the costs and budgets managers steer by; auditors independently check other people's figures; tax accountants compute and defend what is owed. Much of the day is reconciling — making two independent records of the same money agree.
What is the difference between an accountant and a bookkeeper?
A bookkeeper records transactions as they happen — invoices, payments, payroll. An accountant works a level up: adjusting and closing the books, producing financial statements, interpreting them, filing tax and, where licensed, signing opinions a bookkeeper legally cannot. The boundary is blurring as software takes over the recording, pushing bookkeepers toward advisory work and accountants toward review.
Do you need a university degree to become an accountant?
Usually, but less universally than people assume. A US CPA license requires 150 college credit hours in most states, though several states began accepting 120 hours plus extra experience from 2024–25. UK firms hire school-leavers into paid apprenticeships leading to chartered status, the ACCA qualification is open-entry, and India's chartered accountancy course can begin straight from secondary school.
What is the difference between a CPA and a chartered accountant?
They are sibling licenses from different family trees. "Chartered accountant" descends from the royal charters granted to Scottish accounting societies from 1854, and is the credential across the UK, most of the Commonwealth and India. "Certified public accountant" began with New York's 1896 law and is the American license. Each country restricts audit sign-off to holders of its own license.
How long does it take to become a qualified accountant?
Typically five to eight years from leaving school: a three- or four-year degree, then two to four years of professional exams taken alongside supervised work. India's chartered accountancy course is famously attritional — pass rates at the final exam often run between ten and twenty percent per attempt — so many candidates there take considerably longer than the nominal course length.
How much do accountants earn?
The US median for accountants and auditors was about $81,000 in 2024, per the Bureau of Labor Statistics. Newly qualified chartered accountants in London typically earn £50,000–£60,000; newly qualified CAs in India averaged around ₹12 lakh in 2024 campus placements. At the top, Big Four equity partners commonly earn $500,000 to well over $1 million a year.
Will AI replace accountants?
It is already replacing tasks — transaction coding, reconciliation, standard returns — faster than it replaces jobs. The profession is simultaneously short of people: US CPA exam candidates fell by roughly a third between 2016 and 2021, so automation is largely absorbing a shortage. What survives longest is judgment and legal accountability, because software cannot yet sign an audit opinion.
What is the difference between an accountant and an auditor?
Every auditor is an accountant, but auditing is a specific role: independently examining accounts someone else prepared. External auditors, at firms like the Big Four, give public opinions on companies' statements; internal auditors work inside a company testing its own controls, as Cynthia Cooper did at WorldCom. Preparing accounts and auditing those same accounts is forbidden — independence is the whole point.
Embed this ranking
Paste this code into your blog or site — the ranking stays up to date.